Websites for estate agents
Websites for estate and letting agents, built for the audience that actually pays the bills: the vendor deciding who to instruct.
What they need →Websites for mortgage brokers
Websites for mortgage brokers and advisers that explain who you help and how you are paid in plain English, and are built to sit comfortably within the FCA’s financial promotion rules. From £99 a month, live in 3 working days.
Mortgage customers come with a life event and a deadline: a first home, a remortgage because a fixed rate is ending, a move, a buy-to-let, or a complicated situation such as self-employment, a recent credit problem or a later-life borrower. Many are anxious, and many have already been declined or confused by a lender’s website. They search for "mortgage adviser" plus a town, or for their specific situation - "mortgage for self-employed", "first-time buyer mortgage adviser". Estate agents and solicitors refer heavily, so a large share of visitors are checking that the name they were given is credible. Before they call, they want to know whether you are whole of market or work from a panel, whether you charge a fee and when, and whether they can talk in the evening or by video.
When demand peaks. The housing market tends to be busiest in spring and early autumn. Remortgage demand follows when large batches of fixed-rate deals end, and base rate decisions produce bursts of enquiries.
Mortgage broker websites sit under the FCA’s rules on financial promotions, which require communications to be fair, clear and not misleading, and they are usually signed off by the firm’s compliance function or, for appointed representatives, by the network. That combination tends to produce sites that are so cautious they say nothing, or so generic they are indistinguishable from a thousand network templates. The useful middle is specific and honest: who you help, how the process works, how and when you are paid, your FCA status, and the risk warnings firms display (commonly "Your home may be repossessed if you do not keep up repayments on your mortgage"). The site should not quote rates or promise approvals, and any comparison or calculator needs care. Being plain about situations - self-employed, contractors, credit issues - is what makes a small brokerage findable.
The standard first step, and one many clients want outside office hours.
Self-employed, first-time buyer and remortgage clients search for their own case.
Clients sent by agents and solicitors are checking you look established and regulated.
Trust signals we put on every page: FCA authorisation or appointed representative status, with firm reference number · Network name, where an appointed representative · Named advisers with CeMAP or equivalent qualifications · Complaints procedure and Financial Ombudsman Service information · Clear fee disclosure
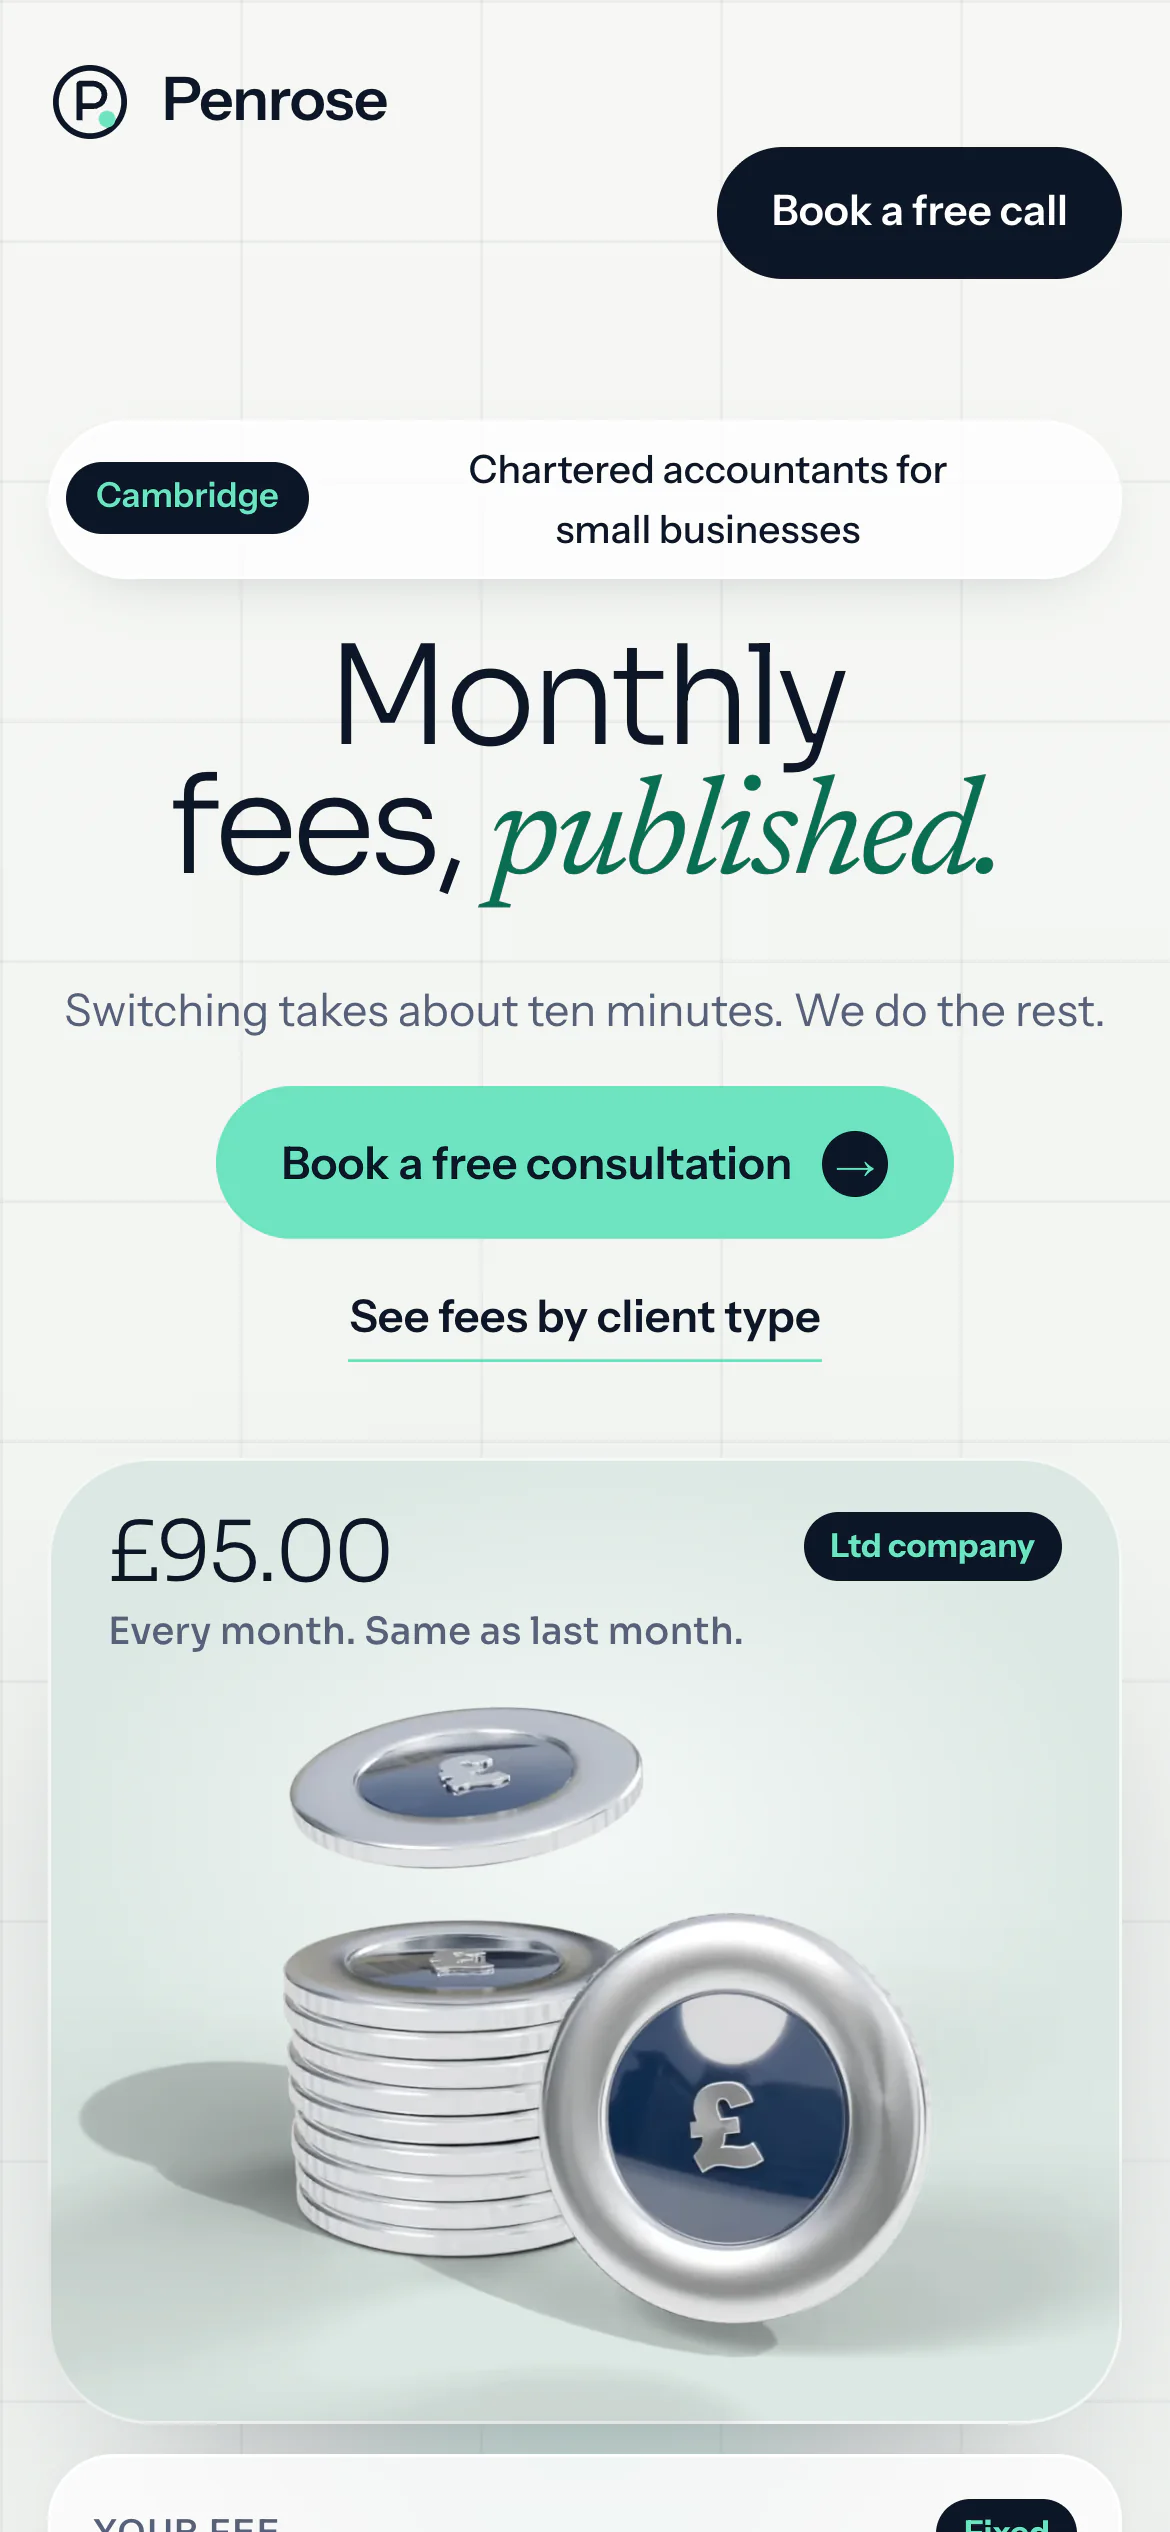
Penrose is designed like a finance app's launch page rather than a practice brochure. A light, ledger-grey hero with a faint grid carries one line in light Urbanist: 'Monthly fees, published', with the last word in Newsreader italic. Below it, a rounded window holds a Blender coin (silver rim, navy enamel, a raised pound sign), and six small dashboard cards float loosely round it: the fixed £95 fee with twelve identical monthly bars, £0.00 hourly billing, filings ticked off, the next deadline, the switching handover with the client manager's photo, and HMRC authorisation received.
19,595
financial services support businesses, including mortgage brokers registered across 375 UK local authorities.
Source: ONS UK Business Counts, SIC 66190, 2025. Open Government Licence v3.0.
| Local authority | Businesses |
|---|---|
| Westminster | 1,010 |
| City of London | 565 |
| Leicester | 480 |
| Leeds | 260 |
| North Yorkshire | 235 |
| Stevenage | 215 |
| Wiltshire | 200 |
| Camden | 195 |
| Ashford | 195 |
| Bristol, City of | 190 |
£299to set up
£99a month
3working days to launch
You approve it before anything goes live.
Designed from scratch, every word written for you, hosting and Google setup included. Or pay £1,795 once and £49 a month with no minimum term.
Websites for estate and letting agents, built for the audience that actually pays the bills: the vendor deciding who to instruct.
What they need →Websites for law firms that route someone in a difficult situation to the right department quickly, and are honest about costs.
What they need →Websites for accountancy practices that answer the two questions every prospect has - do you handle businesses like mine, and what will it cost a month.
What they need →Websites for bookkeepers that say clearly who you work with, which software you use and what it costs a month, so small businesses stop wondering if they need an accountant instead.
What they need →Custom website design for UK businesses of any kind and any size, from sole traders to multi-site companies. £299 to set up, then £99 a month for design, copywriting, hosting and support - live in 3 working days.
Read more →Local SEO setup for small businesses - the technical foundations, Google Business Profile guidance and local relevance that get you found by nearby customers.
Read more →How Nerdsharks pricing works: a setup fee and a monthly plan, or pay for the build outright. What each covers, who should pick which, and the honest 12-month total.
Read →How ChatGPT decides which businesses to name, what it reads when it searches the web, and the practical steps that make yours easier to recommend.
Read →What Google’s AI Overviews and AI Mode are, how they choose sources, what they do to your clicks, and what a small business should actually change.
Read →£299 setup, then £99 a month. Live in 3 working days. Tell us what your business does - we reply the same working day.
Nerdsharks
A real person replies, usually the same working day
Hi 👋 What can we help with? Tap one, or type below.
Got it, thanks. We’ll reply the same working day - check your inbox or phone.